 Beyond Maybe
Paying for college: real aid has an order
Most families work the money problem backwards, falling in love with a school first and hoping the price works out. The honest order: file the FAFSA, chase free money from biggest pool to smallest, and treat loans as a last resort, not aid.
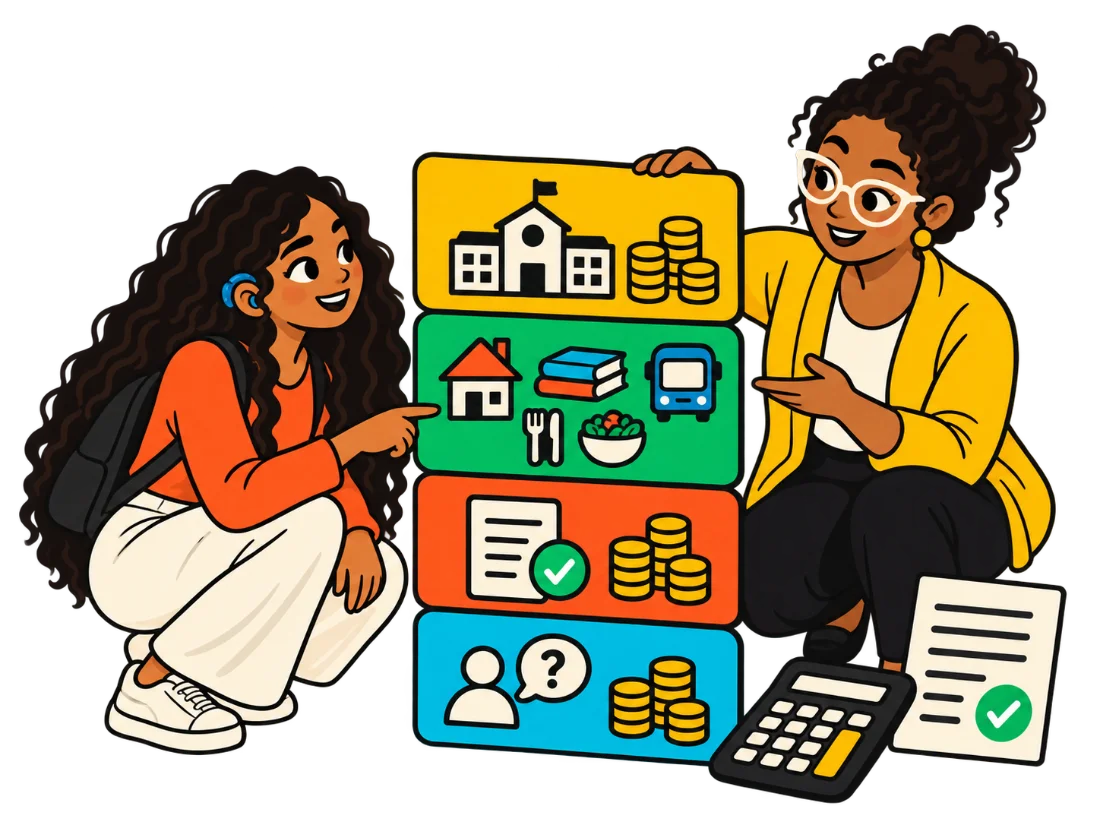
1. FAFSA first, everyone who files is considered
The Free Application for Federal Student Aid unlocks federal grants, state grants, work-study, and most institutional aid. It's free at studentaid.gov, and many state grants are first-come, first-served. Even families who assume they earn too much are often wrong, and many schools require the FAFSA for merit aid too.
The federal Pell Grant, money you never repay, is up to $7,395 per year for the 2026–27 award year, based on need.
2. Institutional money, the biggest discounts
Colleges themselves give the largest scholarships: automatic merit awards, competitive named scholarships, and need-based grants. Wealthy private colleges that “meet full need” can beat state-school prices for lower-income families. Check each school's aid page and apply for its named scholarships, they're often separate applications with real deadlines.
3. State grants
Most states run their own grant programs for residents attending in-state schools, usually keyed off your FAFSA. Deadlines are often earlier than college deadlines.
4. Local and employer money, smaller pools, better odds
Community foundations, service clubs, and employers award thousands of small scholarships with far less competition than national contests. A parent's employer, your own job, and your counselor's local list are all worth one ask each.
5. National scholarships
Big awards are real but very competitive. Worth one or two strong applications, not twenty weak ones.
What loans really are
Loans are not aid, they're your future income, spent early. Federal loans have fixed rates and protections; private loans should be a true last resort. When comparing aid offers, subtract the loans before comparing.
Skip these
- Anyone charging a fee to file the FAFSA or “find scholarships”, both are free.
- Scholarship “lotteries” that harvest your data.
- Advice to skip the FAFSA because “you won't qualify.” File it anyway.
Build your money plan
Beyond Maybe's Money Plan puts these steps in order for your grade and matches you with aid you can actually get.
Open My Money PlanRelated: compare college costs · senior year timeline
Sources
- Federal Student Aid – FAFSA – the application every aid dollar starts from
- Federal Student Aid – Pell Grants – eligibility and maximum awards
- CSS Profile (College Board) – required by some private colleges
Last reviewed September 8, 2026 by the Beyond Maybe team. Spot an error? Email hello@beyondmaybe.org and we’ll correct it.